Renting vs Buying Property in Malaysia: What Makes Sense in 2026?
Key Takeaways
- Flexibility vs Stability: Renting offers mobility while buying provides long-term security.
- True Cost Matters: Buying includes hidden costs beyond monthly loan payments.
- Lifestyle Fit: Your career, goals, and mobility needs heavily influence the right choice.
- Investment Isn’t Guaranteed: Property returns depend on market conditions and strategy.
- Hybrid Strategy: Renting first and buying later is becoming increasingly common.
Why Renting vs Buying Property in Malaysia Is a Big Question Right Now
The debate around renting vs buying property in Malaysia has never been louder. In 2026, rising living costs, shifting job patterns, and changing lifestyle priorities are pushing more Malaysians to rethink what “home” really means.
Across online communities, many are questioning whether buying still makes financial sense in today’s economy, especially with rising interest rates and property prices1.
At the same time, others argue that renting feels like “throwing money away,” while buying builds long-term wealth. The truth lies somewhere in between—and depends heavily on your income, goals, and lifestyle.
The Real Cost of Renting vs Buying (It’s Not What You Think)
Many people assume buying is always cheaper in the long run. But a closer look reveals a more complex reality, especially when hidden costs are factored in2.
When you buy a home in Malaysia, you’re not just paying the monthly loan. You’re also responsible for upfront and ongoing expenses that significantly increase total ownership cost.
- Down payment (often 10%)
- Legal fees and stamp duties
- Maintenance and sinking funds
- Renovation and furnishing
- Interest over decades
Renting, on the other hand, typically involves fewer financial commitments and lower upfront costs, making it more accessible in the short to medium term.
For deeper insight into rental trends and tenant behavior in Malaysia, additional market observations highlight how renting can remain financially efficient depending on timing and location3.
A Visual Breakdown of Costs
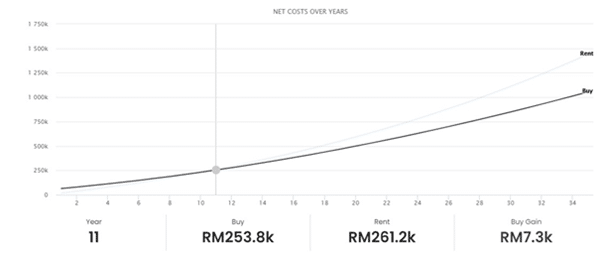
Comparison of long-term cost trends between renting and owning property based on duration of stay and financial commitments
The cost trajectory shows that while buying helps build equity over time, renting often results in lower initial and short-term financial pressure. The tipping point depends largely on how long you plan to stay in one place.
5 Key Questions Malaysians Should Ask Before Deciding
A practical framework suggests that asking the right questions can simplify the decision-making process and remove emotional bias4.
- Can you afford the upfront costs?
- How stable is your income?
- How long do you plan to stay?
- Are you ready for maintenance responsibilities?
- What are your long-term life goals?
These considerations help align your financial decision with your actual life situation rather than assumptions.
Lifestyle Matters More Than You Think
Property decisions are not just about money. Flexibility has become a major factor, especially for those who prioritize proximity to work or the ability to relocate easily5.
Buying offers stability and control, but it also ties you to a fixed location. In a world where remote work and career mobility are more common, this trade-off matters more than ever.
Young Professionals Are Choosing Differently
Recent research shows that many young professionals in Malaysia are delaying homeownership due to financial and lifestyle factors6.
Instead of rushing into property ownership, they are prioritizing flexibility, career growth, and alternative investments, reshaping traditional housing expectations.
The Investment Angle: Can Property Still Make You Money?
Property investment in Malaysia presents mixed outcomes. While some investors generate income through short-term rentals, others face challenges such as vacancy rates and regulatory constraints7.
Discussions also highlight that renting out property immediately is possible, but profitability depends heavily on location, demand, and cost management8.
Additional insights into market oversupply and rental strategies further reinforce that property investment requires careful planning rather than assumptions9.
What Real People Are Saying
Online discussions reveal how divided opinions are. Some emphasize the freedom of renting, while others value the pride and security that comes with ownership10.
Others point out that renting can improve cash flow and allow investment elsewhere, while buying is often seen as a long-term wealth-building strategy11.
The key takeaway is clear: there is no one-size-fits-all answer.
Renting: The Underrated Option
Renting is often misunderstood as wasted money, but it can be a strategic financial decision depending on your situation.
- Greater flexibility for career moves
- Lower upfront financial burden
- Access to prime locations
- Reduced exposure to market risks
In 2026, renting is no longer just temporary—it can be a long-term lifestyle choice.
Buying: Still a Powerful Long-Term Move
Buying property still offers significant benefits, especially for those seeking stability and long-term investment.
- Equity building over time
- Protection from rising rental costs
- Full control over living space
However, these advantages only hold if the property is financially sustainable for the buyer.
The Hidden Risks of Buying Property
Many buyers overlook risks associated with property ownership, including market fluctuations, liquidity challenges, and rising maintenance costs.
Assuming property prices will always increase can lead to poor financial decisions if market conditions shift.
The Hybrid Approach: Rent First, Buy Later
A growing number of Malaysians are adopting a hybrid strategy—renting while building savings and investing elsewhere before committing to property ownership.
This approach provides flexibility while reducing financial risk, especially in uncertain economic conditions.
Where to Start Your Property Search
For those considering buying, platforms like Property Guru can help explore listings and understand pricing trends.
However, evaluating affordability, long-term plans, and total cost remains essential before making any commitment.
So, Should You Rent or Buy in Malaysia?
It depends on your personal situation, financial stability, and future plans.
- Choose renting if you value flexibility and mobility
- Choose buying if you have stable income and long-term plans
Both options can be smart when aligned with the right strategy.
Final Thoughts: It’s Not About the Property—It’s About the Strategy
The conversation around renting vs buying property in Malaysia has evolved significantly.
In 2026, the focus is no longer on which option is better, but which one fits your life, finances, and goals.
Making the right decision requires careful planning, realistic expectations, and a clear understanding of your priorities.
At the end of the day, a home is not just an asset—it’s where your life happens.
Frequently Asked Questions
Question: Is renting cheaper than buying in Malaysia?
Answer: Renting can be cheaper in the short to medium term due to lower upfront costs and fewer financial responsibilities, but long-term costs depend on individual circumstances.
Question: When does buying become more beneficial than renting?
Answer: Buying typically becomes more beneficial if you plan to stay long-term and can comfortably afford all associated costs, allowing you to build equity over time.
Question: Can renting still help build wealth?
Answer: Yes, if the money saved from renting is invested wisely, it can generate returns and contribute to long-term financial growth.