Shariah-compliant Home Financing: A Complete Guide for Homebuyers in 2026
Key Takeaways
- Interest-Free Financing: Shariah-compliant home financing avoids interest and focuses on ethical contracts.
- Asset-Based Structures: Financing is built on real assets, trade, or partnerships rather than lending money.
- Multiple Models: Common structures include Murabahah, Musharakah, and Tawarruq.
- Growing Demand: Increasing global interest in ethical and transparent finance is driving adoption.
- Ongoing Evolution: Industry reforms and research are improving compliance and transparency.
Introduction to Shariah-compliant Home Financing
In 2026, the global conversation around ethical finance is growing fast—and at the center of it is Shariah-compliant home financing. For many homebuyers, especially within Muslim communities, the focus is no longer just affordability but also aligning financial decisions with personal values.
This shift reflects a deeper demand for fairness, transparency, and trust in financial systems. Islamic home financing models are designed to avoid interest (riba) and instead emphasize shared risk, asset-backed transactions, and ethical agreements.
What Is Shariah-compliant Home Financing?
Shariah-compliant home financing allows individuals to purchase property without using interest-based loans. Instead of lending money, financial institutions structure transactions around real assets and trade-based contracts.
In a conventional mortgage, a bank lends money and earns interest. In contrast, Islamic financing involves the bank either purchasing and selling the property to the buyer or entering into a partnership arrangement, earning profit through agreed terms rather than interest1.
Why It Matters in 2026
The rise of Shariah-compliant financing is closely tied to growing concerns about trust in financial systems. Discussions in regions like Malaysia highlight the need to ensure these financing models truly reflect principles of justice, fairness, and transparency2.
Ethical financial practices emphasizing fairness, shared ownership, and transparent agreements
As demand increases, so does scrutiny. Buyers are asking whether products are genuinely compliant, whether they offer fair protection, and whether institutions are transparent in their dealings.
How Shariah-compliant Home Financing Works
Islamic home financing includes several structures designed to enable homeownership without interest.
Murabahah (Cost-Plus Financing)
In this model, the bank purchases the property and sells it to the buyer at a higher agreed price, which is paid in installments. The profit is fixed upfront, ensuring transparency. Some banks incorporate commodity trading mechanisms to maintain compliance3.
Musharakah (Partnership Model)
This model involves shared ownership between the buyer and the bank. Over time, the buyer gradually purchases the bank’s share while potentially paying rent for the portion not yet owned.
Tawarruq (Commodity-Based Financing)
Tawarruq involves structured commodity transactions to generate financing without interest. However, it has sparked scholarly debate, particularly regarding compliance risks and financial authenticity4.
Real Products in the Market
Many banks now offer Shariah-compliant home financing products tailored to different buyer needs, showing how the industry is evolving to remain competitive and accessible5.
The Role of Shariah Boards
Every Islamic financial institution operates under a Shariah Board, which ensures that products and transactions comply with Islamic law. These boards review, approve, and monitor financial structures to maintain integrity and trust6.
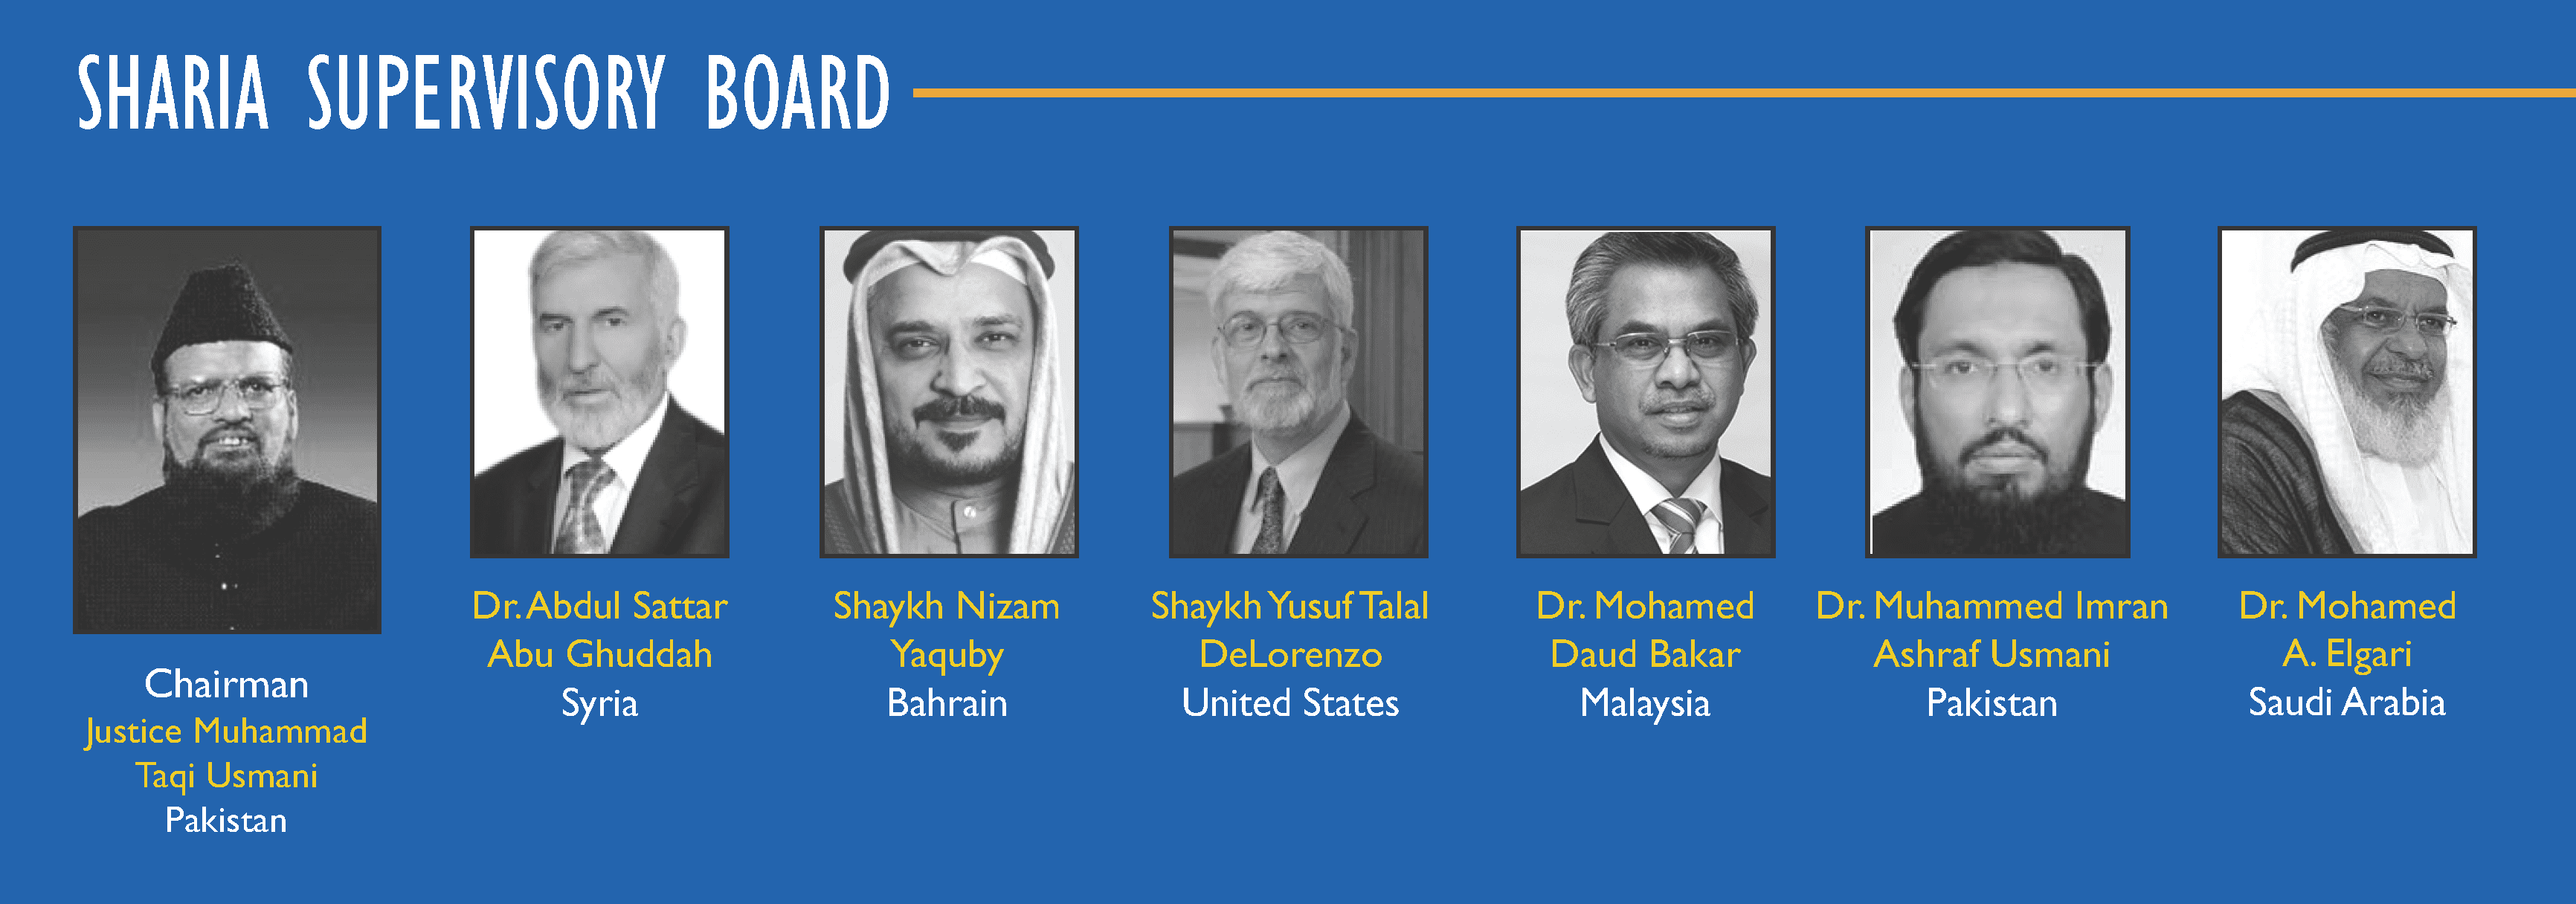
The Challenge of True Compliance
Achieving full compliance remains a challenge. Researchers continue to refine structures, eliminate questionable elements, and improve transparency to ensure alignment with Islamic finance principles7.
What Do Consumers Think?
Consumer trust plays a major role in adoption. Studies show that buyers are more likely to choose Islamic financing when they understand how it works and believe it is genuinely compliant8.
Benefits of Shariah-compliant Home Financing
- Ethical and Transparent: Clear contracts with no hidden interest.
- Risk Sharing: Some models promote shared ownership and responsibility.
- Value Alignment: Meets religious and ethical expectations.
- Growing Availability: Increasing number of competitive products.
Potential Drawbacks to Consider
- Complexity: Structures may be harder to understand.
- Pricing: Costs can vary depending on the model.
- Scholarly Debate: Not all structures are universally accepted.
How to Choose the Right Option
- Understand Contracts: Learn the differences between Murabahah, Musharakah, and Tawarruq.
- Check Governance: Ensure a credible Shariah Board oversees the product.
- Review Terms: Examine profit rates and payment structures carefully.
- Compare Options: Evaluate different providers before deciding.
The Future of Shariah-compliant Home Financing
The future of Islamic home financing points toward greater transparency, stronger regulations, and continued innovation. As reforms progress, these models may attract a broader audience seeking ethical financial alternatives.
Final Thoughts
Shariah-compliant home financing represents a shift toward fair, transparent, and value-driven finance. By replacing interest-based lending with trade and partnership models, it offers a more balanced approach to homeownership.
For buyers, understanding the structure and asking the right questions is key to choosing a solution that aligns with both financial goals and personal values.
Frequently Asked Questions
Question: What makes Shariah-compliant financing different from conventional mortgages?
Answer: It avoids interest and instead uses asset-based transactions or partnerships where profit is agreed upfront.
Question: Is Shariah-compliant home financing only for Muslims?
Answer: No, it is available to anyone interested in ethical and interest-free financial solutions.
Question: Are these financing options more expensive?
Answer: Costs can vary depending on the structure and provider, but many products are designed to be competitive with conventional mortgages.